CSE Ends Week on Positive Note as Banking Stocks Lift Daily Indices Despite Weekly Losses
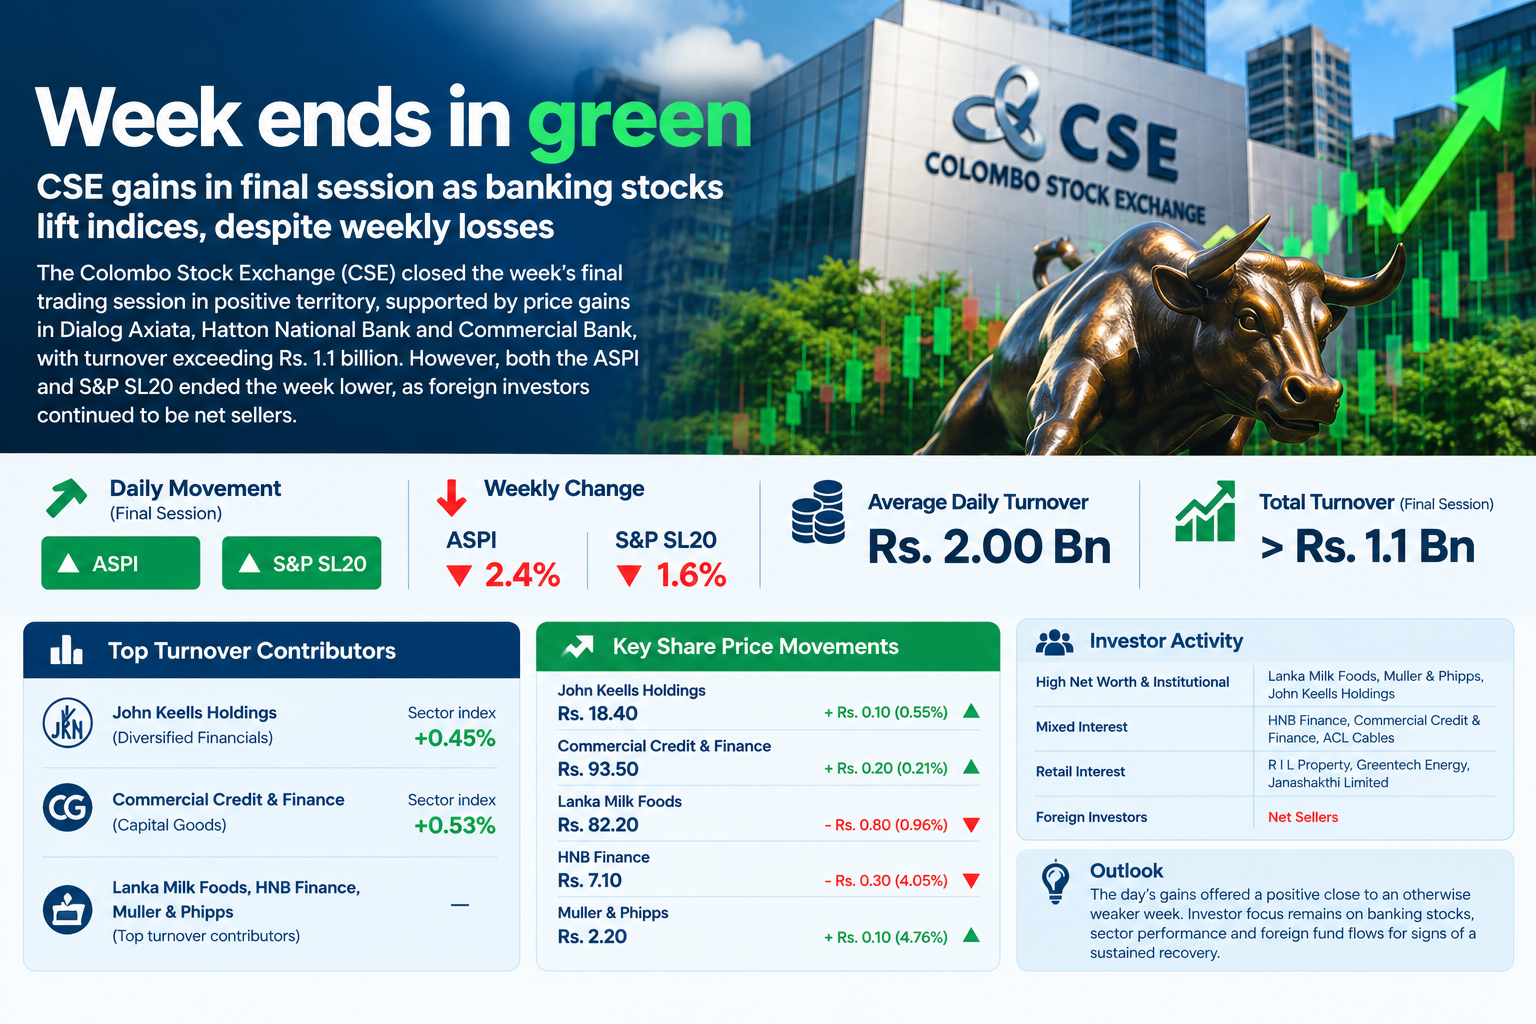
COLOMBO, October 11, 2026 — Sri Lanka’s stock market ended the week’s final trading session in positive territory, supported by price gains in Dialog Axiata, Hatton National Bank (HNB) and Commercial Bank, with turnover exceeding Rs. 1.1 billion. However, the broader market remained under pressure over the week, as both benchmark indices recorded losses amid subdued foreign investor participation.
The All Share Price Index (ASPI) and the S&P SL20 gained ground during the final session, reflecting buying interest in selected telecommunications and banking counters. Despite the daily recovery, the ASPI declined 2.4% over the week, while the S&P SL20 fell 1.6%. Average daily market turnover stood at approximately Rs. 2.00 billion.
High-net-worth and institutional investor activity was observed in Lanka Milk Foods, Muller & Phipps and John Keells Holdings (JKH). Mixed investor interest was recorded in HNB Finance, Commercial Credit & Finance and ACL Cables, while retail participation centred on R I L Property, Greentech Energy and Janashakthi Limited. Foreign investors remained net sellers, adding to concerns over overseas investor sentiment.
The Diversified Financials sector was the largest contributor to market turnover, driven by activity in John Keells Holdings, while the sector index gained 0.45%. JKH shares rose Rs. 0.10, or 0.55%, to close at Rs. 18.40.
The Capital Goods sector ranked as the second-largest contributor to turnover, supported by trading in Commercial Credit & Finance. The sector index advanced 0.53%, while Commercial Credit & Finance shares gained Rs. 0.20, or 0.21%, to close at Rs. 93.50.
Other notable turnover contributors included Lanka Milk Foods, HNB Finance and Muller & Phipps. Lanka Milk Foods declined Rs. 0.80, or 0.96%, to close at Rs. 82.20. HNB Finance fell Rs. 0.30, or 4.05%, to Rs. 7.10, while Muller & Phipps advanced Rs. 0.10, or 4.76%, to close at Rs. 2.20.
The session’s gains offered a positive finish to an otherwise weaker week, with selective buying helping lift the benchmark indices. Nevertheless, the weekly declines and continued net selling by foreign investors suggest that the market has yet to establish a broad-based recovery.
Investor attention will remain focused on banking and heavyweight counters, sector-level activity and foreign fund flows for indications of whether the market can regain momentum in the coming sessions.